When the relationship breaks down, company law decides what happens next – and it does not work the way most people expect.
Most private companies are built on a relationship rather than a document. Two or three people go into business together, agree how things will work over a coffee or in an email, and get on with trading. It works, often for years.
Then something changes. One person’s contribution falls away while another’s grows. Someone wants to take money out and someone else wants to reinvest. Someone sets up a second venture. Or there is simply a falling-out of the kind that has nothing to do with business at all. At that point the informal understanding stops being enough, and what governs the situation is the company’s constitution and the Companies Act 2006 – which is concerned with rights and process rather than with who has behaved better.
This article outlines how shareholder disputes in private companies work under the law of England and Wales, and where the pressure points usually are. If your business is a partnership or an LLP the framework is different, and the comments below will not apply.
Start with the paperwork, not the argument
The first question is always what the articles of association and any shareholders’ agreement actually say. Between them they may already answer the dispute: whether shares must be offered to the other shareholders before being sold, how they are to be valued, whether a departing shareholder is a “good” or “bad” leaver, whether there is a deadlock procedure, and whether anyone has a veto or enhanced voting rights. Where those documents exist and are well drafted, the dispute is usually about applying them. Where they do not – and in a great many owner-managed companies there is no shareholders’ agreement at all – the parties fall back on the default statutory position, which is rarely what either of them assumed.
What your percentage actually buys
Shareholders tend to overestimate what a stake delivers – and, more often still, to assume that the percentages settle the question by themselves. They do not. Before looking at the thresholds it is worth understanding how a vote is actually taken, because the two things work together and the outcome can differ markedly depending on the method used.
Unless the articles provide otherwise, a resolution put to a general meeting is decided in the first instance on a show of hands, and on a show of hands each member present in person has one vote whatever the size of their holding (section 284(1) of the Companies Act 2006). A 90% holding and a 5% holding count equally. The consequences of that are easily overlooked. The default quorum under the model articles is two qualifying persons, so where two minority shareholders attend a properly convened meeting they form a quorum between them; if they vote the same way, an ordinary resolution can be carried on a show of hands without the support of the majority shareholder and, if that shareholder does not attend, without their involvement at all. Nothing in the general law requires the majority holder to be present, only that they be given proper notice.
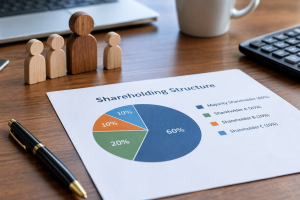
What answers that is a poll. On a poll, voting is by shares – one vote for each share held (section 284(2)) – and it is here that the percentages do the work most people assume they do throughout. A poll may be demanded by the chair, and under section 321 by at least five members entitled to vote, by members representing at least 10% of the total voting rights, or by holders of shares representing at least 10% of the paid-up voting capital; the articles cannot cut those rights down. A majority shareholder who attends can therefore demand a poll and carry the meeting on the strength of the holding. One who stays away, or who attends but does not think to call for a poll, may find the show-of-hands result stands.
The articles ought to spell all of this out, and many do. Not all of them do, and the position on proxies, on the chair’s casting vote and on who may demand a poll varies from company to company. It is worth reading them before either side plans a meeting around what it believes the numbers to be. Written resolutions work differently again: they are decided by reference to shareholdings rather than by a count of those present (section 283), so the show-of-hands point does not arise – though, as set out below, a director cannot be removed that way.
The thresholds themselves are these. More than 50% of the votes cast carries an ordinary resolution, which includes removing a director. More than 25% of the votes cast blocks a special resolution, and therefore changes to the articles – note that these thresholds bite on votes cast rather than on issued capital, so on a poor turnout a smaller holding can be decisive. Holders of at least 5% of the paid-up voting capital can require the directors to call a general meeting under section 303 of the Companies Act 2006.
Below that, a percentage buys very little in terms of control – but it is worth knowing that there is no minimum shareholding for the most important remedy in this area. Any member can bring an unfair prejudice petition, however small the holding. The word doing the work there is member: someone whose shares are held through a nominee, or who is only a beneficial owner and is not entered in the register of members, is generally not a member and cannot petition.
You probably cannot see the books
This is the point that causes the most frustration. There is no general right for a shareholder to inspect a company’s documents. You are entitled to the annual accounts and reports (section 423), to inspect the register of members (section 116), to inspect minutes of general meetings and members’ written resolutions (section 358), and to see directors’ service contracts (sections 228 and 229). That is broadly the extent of it.
There is no right to board minutes, management accounts, bank statements, contracts, budgets or correspondence. Even the register of members is filtered: a company served with a request must either comply or apply to the court within five working days, and the court will direct that it need not comply if the request is not sought for a proper purpose – the purpose having to relate to your interest as a member and the exercise of shareholder rights (section 117; Burry & Knight Ltd v Knight [2014] EWCA Civ 604, where the Court of Appeal made clear the onus is on the company to satisfy the court of an improper purpose).
An important qualification: this describes the position of a shareholder as a shareholder. If you are also still a director, your right of access to the company’s books and records is considerably wider while you remain in office. Where neither applies, formal proceedings and the disclosure that comes with them are sometimes the only realistic route to the documents.
Removing someone as a director changes less than you think
A director can be removed by ordinary resolution under section 168, notwithstanding anything in any agreement with them. Two points about the mechanics matter more than they may appear to. First, the resolution must be passed at a general meeting of the shareholders. It cannot be done by written resolution (section 288(2)), and it cannot be done by the board: a decision of the directors, however unanimous and however it is minuted, has no effect on a person’s office as director under section 168. The point is easily missed in a small company where the same individuals sit on both sides and meetings are not always convened with much formality. Special notice of at least 28 days must be given to the company (section 312), and the director has the right to be heard at the meeting and to have written representations circulated to members (section 169).
Second, the director is not a bystander at that meeting. If they are also a shareholder they vote on the resolution to remove them in the ordinary way, like any other member. There is no rule excluding them from the count, and no read-across from the position of a director who is interested in a transaction. A director-shareholder holding half the votes can defeat the resolution outright; a smaller holding may be enough where turnout is poor, since the threshold is a majority of the votes cast rather than of the issued capital. Anyone planning a removal needs to be confident of the arithmetic on the day, and of how the vote will be taken, before giving special notice.
There are three things removal does not do. It does not touch their shares – absent a compulsory transfer provision in the articles or a shareholders’ agreement, they remain a shareholder. It does not extinguish any claim for compensation or damages for loss of office or employment, which section 168(5) expressly preserves. And it may itself be the unfairly prejudicial conduct that a court later acts on: in Stevens v Kyte [2026] EWHC 1231 (Ch) the dismissal and removal of one of three equal participants in the business were found to be pretextual, aimed at forcing a sale of his interest at as low a price as possible, and a breach of fiduciary duty.
It is also worth checking the articles before counting the votes. A weighted-voting provision – of the kind upheld in Bushell v Faith [1970] AC 1099 – gives a director-shareholder enhanced votes on a resolution to remove him. Section 168 still applies and the resolution can still be proposed; it simply loses on the count.
The main remedy: unfair prejudice
Section 994 allows a member to petition where the company’s affairs are being or have been conducted in a manner unfairly prejudicial to the interests of members generally or of some part of them, including at least the petitioner. If the petition succeeds the court may make any order it thinks fit (section 996), and in practice the usual outcome is an order that the other shareholders or the company buy the petitioner’s shares.
Two threshold points do a lot of work. The conduct must be conduct of the company’s affairs, and the prejudice must be to your interests as a member. A falling-out between shareholders personally is not enough: in Brierley v Howe [2024] EWHC 2789 (Ch) parts of a petition were struck out because a dispute about an agreement to transfer shares between two shareholders was not conduct of the company’s affairs.
Unfairness also has to be anchored to something. Following O’Neill v Phillips [1999] 1 WLR 1092, it generally means breaching what was agreed, or using strict legal powers in a way that equity will not permit. Where the company is a “quasi-partnership” – formed on a personal relationship of mutual confidence, with an understanding that the participants would be involved in management – exclusion from management is a classic route to relief. The concept comes from Ebrahimi v Westbourne Galleries Ltd [1973] AC 360 and remains central.
Directors’ duties feed into this. Those duties are owed to the company, not to individual shareholders (section 170(1)), and a shareholder cannot bring a personal claim for loss that merely reflects the company’s own loss. That rule does not, however, limit the court’s powers on an unfair prejudice petition, and a fall in the company’s value caused by the conduct complained of feeds directly into the valuation of the shares to be bought out. A breach of duty is very often the engine of a successful petition. In Saxon Woods Investments Ltd v Costa [2026] UKSC 21 the Supreme Court held that good faith under section 172 extends not only to a director’s thinking but to their conduct in pursuit of what they believe to be the best course – a director cannot pursue their own view by covert or disloyal means, however sincerely it is held – and upheld an unconditional buy-out.
Valuation is often worth more than the merits
Two questions decide the money: whether a minority discount applies, and at what date the shares are valued. Neither has a fixed answer.
In a quasi-partnership the court will commonly order a purchase on a proportionate basis with no minority discount, as in Stevens v Kyte. But that is the exercise of a wide discretion rather than a rule, and it depends on the quasi-partnership finding being made: in Wells v Hornshaw [2024] EWHC 330 (Ch) the company was held not to be a quasi-partnership, the shareholders’ agreement governed the valuation, and a minority discount was applied. On timing, the starting point is the date of the order (Profinance Trust SA v Gladstone [2001] EWCA Civ 1031), but the court will go earlier or later to reach a fair result – in Chave v Farnsworth [2026] EWHC 970 (Ch) an earlier date was chosen because the value at judgment had been depressed by the very conduct complained of, while in Stevens v Kyte a later date was chosen, the court declining to give the petitioner a one-way bet.
If you want to buy the other side out, get the offer right
Where the complaint is exclusion from management, a reasonable offer to buy the petitioner’s shares at fair value will ordinarily remove the unfairness and defeat a petition. It will not necessarily answer a petition founded on something else – misappropriation of assets, or excessive remuneration already extracted – where a buy-out does not cure the past prejudice. The features the court looks for include a fair value, ordinarily without a minority discount; determination by a competent expert acting as an expert if value is not agreed; equal access to information bearing on value and an equal right to make submissions to the expert; and, where the offer comes after costs have been incurred, an offer to meet those costs.
Timing is critical. In Magic Investments SA v Broadbent [2026] EWCA Civ 711 the Court of Appeal reinstated a petition that had been struck out, where the offer came months after the petition was presented and made no provision for costs. The offer is worth making early – before proceedings, if possible.
Deadlock, and the winding-up option
In a 50/50 company neither side can pass an ordinary resolution, so neither can remove the other or force a distribution, and the company drifts. The court can order a meeting to be held where it is impracticable to call one in the ordinary way (section 306), and that can rescue a frustrated majority: in Union Music Ltd v Watson [2003] EWCA Civ 180 an order was made where the holdings were 51/49. It will not help in a true 50/50 company. The power is procedural, and it is not to be used to break a deadlock between equal shareholders (Ross v Telford [1998] 1 BCLC 82) or to override a provision conferring what is in substance a veto (Harman v BML Group Ltd [1994] 1 WLR 893).
Where there is genuine deadlock and an irretrievable breakdown, a company can be wound up on the just and equitable ground under section 122(1)(g) of the Insolvency Act 1986, as it was in Dosanjh v Balendran [2025] EWHC 507 (Ch). It should be approached with care. Winding up realises break-up value rather than going-concern value, a pending petition can disrupt the company’s banking and dealings with its assets, and paragraph 22.1 of the Practice Direction – Insolvency Proceedings draws attention to the undesirability of asking as a matter of course for a winding-up order as an alternative to relief under section 994.
The court can now order you to mediate
This has changed, and older commentary is out of date. In Churchill v Merthyr Tydfil County Borough Council [2023] EWCA Civ 1416 the Court of Appeal held that the court may lawfully order parties to engage in non-court dispute resolution, provided the order does not impair the right to proceed to a judicial hearing and is proportionate. The Civil Procedure Rules were amended with effect from 1 October 2024 to add an express case management power to order parties to engage in alternative dispute resolution (rule 3.1(2)(o)), and to make failure to comply with such an order, or unreasonable failure to engage, part of the conduct the court takes into account on costs (rule 44.2(5)(e)). Silence in response to an invitation to mediate is itself likely to be treated as unreasonable (Northamber plc v Genee World Ltd [2024] EWCA Civ 428).
That is not only a procedural point. Shareholder disputes are expensive, slow and absorbing, and they are fought while the business still has to be run. The commercial answer is frequently a negotiated exit at a sensible valuation, reached before either side has spent a disproportionate amount establishing who was right.
If you are heading into one
Take advice early, before positions harden and before anything is put in writing that will be read out later. Preserve documents and keep a contemporaneous record. Be careful about decisions taken while a dispute is live, and about drawings, payments to connected parties and new ventures – that conduct becomes the evidence. And if your business has no shareholders’ agreement, that is where most of these disputes could have been prevented.
Facing a shareholder dispute, or worried one is coming? Our corporate and dispute resolution solicitors advise on the options, on negotiating an exit and on unfair prejudice proceedings, subject to our usual conflict checks. Please get in touch to discuss your situation.
This article is general information about private companies incorporated in England and Wales, as at August 2026. It does not address partnerships, limited liability partnerships, listed companies or companies incorporated elsewhere. It is not legal advice, no solicitor and client relationship arises from reading it, and it should not be relied upon: outcomes in shareholder disputes turn heavily on the company’s constitution and the particular facts, and the law may have changed since the date given. Please take advice on your own position.